Before you consider major renovations, focus on high-impact, low-cost projects. These seven repairs are proven to improve buyer perception, translate to higher offers, and help your home sell faster
Dated: November 10 2025
Views: 10
Being financially prepared before engaging a real estate agent shows you are a serious and qualified buyer, which gives you a strong advantage in a competitive market.
Here are the 5 essential financial steps, focusing on loan pre-approval, credit, and down payment:
Before a lender tells you what they will lend, you need to decide what you can comfortably afford.
Calculate Affordability: Look beyond the mortgage payment. Tally up all potential monthly housing costs:
Principal and Interest (P&I)
Property Taxes
Homeowner's Insurance (HOI)
Private Mortgage Insurance (PMI, if your down payment is less than 20%)
Homeowner's Association (HOA) fees, if applicable.
Set a Down Payment Goal: Decide how much you can realistically put down (e.g., 3%, 5%, 10%, or the coveted 20% to avoid PMI). You also need to save for closing costs, which are typically 2% to 5% of the loan amount.
Organize Funds: Consolidate your savings and ensure all funds needed for the down payment and closing costs are in an easily accessible and verifiable account (like a checking or savings account) for at least 60 days. Lenders will require statements to verify the source of your money.
Your credit score is the single biggest factor in determining the interest rate you'll be offered, which can save you tens of thousands of dollars over the life of the loan.
Obtain Your Reports: Pull your credit reports from all three major bureaus (Experian, Equifax, and TransUnion) and review them thoroughly.
Dispute Errors: Immediately dispute any errors or incorrect information, as this process can take weeks or months.
Improve Your Score: Focus on:
Paying down high-interest debt, especially credit card balances, to lower your credit utilization ratio (the amount of credit used vs. the amount available). Keeping this below $30$ is ideal.
Avoid opening new credit accounts or taking out new loans.
Avoid closing old credit accounts, as this can negatively impact your score by reducing your average credit history length.
Lenders require extensive paperwork for a pre-approval and final underwriting. Having these documents ready makes the pre-approval process faster and smoother.
Income Verification: Pay stubs (last 30 days), W-2 forms (last two years), and complete personal tax returns (last two years). If you are self-employed, you will need more detailed documentation like 1099s and Profit & Loss statements.
Asset Verification: Statements from all checking, savings, investment, and retirement accounts (last two months).
Debt/ID Verification: Driver's license, Social Security number, and information on any other debts (car loans, student loans, etc.).
This is the most critical step before calling an agent. A pre-approval is a conditional commitment from a lender to give you a specific loan amount based on their verified review of your finances.
Shop Lenders: Talk to multiple lenders—a large bank, a local credit union, and a mortgage broker—to compare interest rates, fees, and customer service. Do this within a 14-45 day window to minimize the impact of multiple hard credit inquiries.
Receive Your Letter: The resulting Pre-Approval Letter is what you will show a real estate agent and what you will submit with any offer on a home. It proves you are a serious, qualified buyer who can secure financing.
Understand Your Limit: The pre-approval letter states the maximum you qualify for; stick to the comfortable budget you set in Step 1.
Once you have your pre-approval, you must not make any major financial changes until after closing. Lenders will verify your financial status again just before closing.
DO NOT quit your job, change jobs, or become self-employed.
DO NOT take out new loans (e.g., a new car or furniture).
DO NOT open new credit cards.
DO NOT make any large, unexplainable deposits or withdrawals from your bank accounts. All funds must be sourced and trackable.
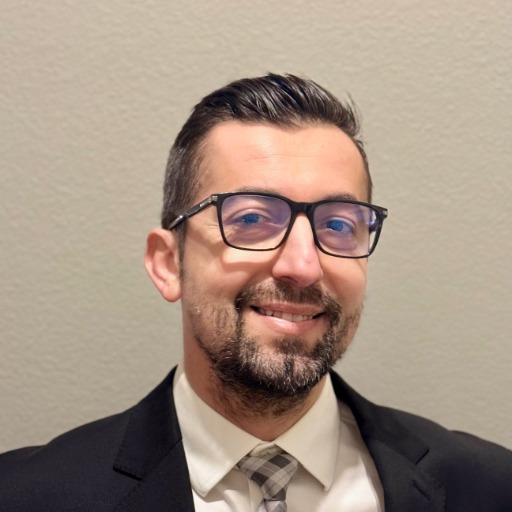
Born across the big pond in beautiful sunny Macedonia, the land of Alexander The Great. Came to the States in 1995 in Oklahoma to chase the 'American Dream" and proud to call this country home ever si....
Before you consider major renovations, focus on high-impact, low-cost projects. These seven repairs are proven to improve buyer perception, translate to higher offers, and help your home sell faster
Being financially prepared before engaging a real estate agent shows you are a serious and qualified buyer, which gives you a strong advantage in a competitive market.Here are the 5 essential
The Bentonville, Arkansas, housing market is generally considered to be a balanced market right now, which means that supply and demand are roughly equal.However, the Northwest Arkansas region is
Should you require assistance in navigating our website or searching for real estate, please contact our offices at 479-756-1003.
 Northwest Arkansas Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Weichert, Realtors® - The Griffin Company - Springdale may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 26, 2026 8:29 PM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Weichert, Realtors® - The Griffin Company - Springdale may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 26, 2026 8:15 PM UTC
Show More...
